
Ferrochrome is a special important alloy additive in the steelmaking industry, it has High status. China is one of the biggest export countries of low carbon ferrochrome, and the price of the low-carbon ferrochrome and market has an important impact on every steel plant, casting plant Automotive Industry, real estate from every county. This article mainly introduces low-carbon ferrochrome the whole market status in China and the outlook for China’s low-carbon ferrochrome prices and market in 2025.

The overall situation of China’s low carbon ferrochrome in 2024
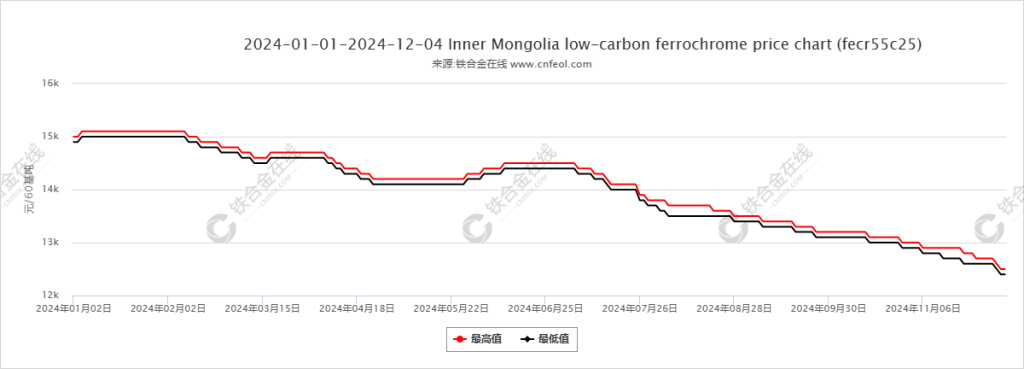
The overall price of China’s low carbon ferrochrome in 2024 showed a trend of opening high and closing low. The average price of low carbon ferrochrome was 14010.75 yuan/60 base tons, with the highest price reaching 15050.00 yuan/60 base tons and the lowest price at 12450.00 yuan/60 base tons. In December, the domestic low-carbon ferrochrome price fell again, reaching 12400 yuan/60 base tons.
China’s low carbon ferrochrome market forecast for 2025
By 2025, the global economy will slowly recover, the Russian-Ukrainian war and the Israeli-Palestinian conflict will stop, and the demand for infrastructure construction will increase greatly, stimulating the production capacity of steel mills and increasing the demand for some stainless steels and special steels, thereby driving up the price of ferroalloys and increasing demand.
In 2025, the automobile and real estate industries in China and other developing countries will continue to develop, which will inevitably drive the demand for steel, thereby increasing the demand for ferroalloys and low-carbon ferrochrome, because ferrochrome is the raw material for stainless steel products.
The demand and supply of chromium ore are increasing. The price in South Africa is an important factor in the rise and fall of chromium ore. Its high price will continue until the first half of 2025. However, in the second half of the year, with the poor steel market, the possibility of downstream forcing upstream to make price adjustments will increase, and port inventory will be restored after the iron price fluctuates. Therefore, the price and market of low-carbon ferrochrome will also have a positive trend by the second half of 2025.
Due to the backlog of ferrochrome plants in Indonesia and the ramp-up of domestic ferrochrome production capacity, the domestic supply of high-carbon ferrochrome will increase significantly, while downstream demand, especially stainless steel demand for ferrochrome, will slow down. It is expected that the pressure on the ferrochrome supply side will increase further in 2025, and the pricing initiative of iron prices on downstream will be weakened.