
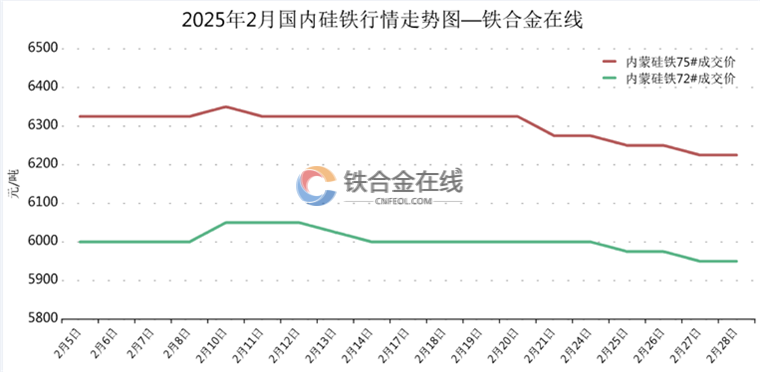
In February, due to the Spring Festival holiday, the price trend of ferrosilicon was downward. Although the ferrosilicon futures market was very good after the Spring Festival, the market fell rapidly in the absence of interest support. The downstream demand of the steel industry and other industries recovered slowly, and buyers waited and watched without purchasing.
At the end of February, the Chinese market price of ferrosilicon was generally 5,800-6,000 yuan per ton for ferrosilicon 72, and 6,100-6,250 yuan/ton for ferrosilicon 75. The ex-factory price of natural ferrosilicon blocks also fell by 50-150 yuan/ton compared with the previous month. As a leading ferroalloy manufacturer in China, this article interprets the price trend of ferrosilicon in the Chinese market in February and analyzes the price trend of ferrosilicon in March.
Ferrosilicon price trend in early and mid-February
Specifically, the market began to recover during the Spring Festival holiday in early February. The futures market had a good start driven by silicon manganese. Factories followed the market to raise prices. In the early February, the market price of silicon 72 was 5900-6150 yuan per ton, and the price of ferrosilicon 75 was 6300-6400 yuan/ton for natural blocks ex-factory, which was 50 yuan/ton higher than before the holiday.
In the middle of the month, the price of semi-coke fell, Zhongwei continued to resume production, and the price of steel bidding fell. The market fell significantly, and the spot price shipments were relatively active. The factory prices were under pressure to fall. In the middle of the month, the market price of ferroislicon72 was 5800-6000, and ferrosilicon75 was 6150-6300 yuan/ton for natural blocks ex-factory, which was 100-150 yuan/ton lower than the early month.
Ferrosilicon production in China in February
The latest statistics show that in February, there were 76 ferrosilicon enterprises in production nationwide, with 269 ore-fired furnaces in production. The average operating rate of ferrosilicon in February was 51.85%, up 0.57% from January, and the output was expected to be 452,000 tons, down 10,300 tons from January and up 12,800 tons from the same period last year, a year-on-year increase of 2.91%. The cumulative output from January to February 2025 was 914,300 tons, up 4,600 tons from the same period last year.
Ferrosilicon plant operation status in February
In terms of the start of work this month: In Bayannur City, Inner Mongolia, Xingang Chemical converted one metal silicon unit to high-purity ferrosilicon in the middle of the month. Gansu Tengda converted two high-silicon furnaces to produce ferrosilicon at the beginning of the month, and stopped one unit in the second half of the month. Qinghai Jinfeng increased production by one unit. Ningxia Shengjin resumed production of four units, Ruizi Lian converted one 97 silicon unit to produce high-purity ferrosilicon, Xinhua overhauled one unit in the middle of the month, Teradyne overhauled one unit in the middle of the month, Jinyuan Chemical overhauled one unit in the second half of the month, and Haoyue overhauled one unit at the end of the month. Shaanxi Jinleiyuan stopped two units during the Spring Festival, and Jinwantong added one unit in the middle of the month. There were no changes in Xinjiang, Sichuan, and Chongqing.
Price trend of downstream ferrosilicon products
In terms of magnesium metal: In February, magnesium ingots were stable first and then fell, with the market price at the end of the month at 15,400 yuan/ton, down 500-600 yuan/ton from the beginning of the month. In February, the magnesium market was mainly affected by factors such as slow recovery on the demand side, weakened cost support, and the lack of relief in the contradiction between supply and demand. The downstream waited and watched to suppress prices, bearish sentiment was obvious, market transactions were sluggish, and magnesium factory prices were under pressure to fall.
Ferrosilicon price forecast for March
From the perspective of cost, the price of lignite has fallen to a low level, and the subsequent decline is expected to narrow. Pay attention to the settlement of electricity prices in early March. From the perspective of supply, the daily output of ferrosilicon is 16,260 tons (2.17-2.23). There will be factory maintenance this week, and the output is expected to drop slightly. From the perspective of demand, steel mills are slow in bidding and continue to maintain a low inventory strategy. Magnesium plants are reluctant to purchase due to the continuous decline in magnesium prices. Casting demand is expected to improve in March, and exports are still under pressure. In March, pay attention to whether there are favorable stimuli on the macro side, and pay attention to the reduction in ferrosilicon production on the fundamental side. It is expected that the silicon market will start weakly in March. If the reduction in production is obvious, it may be weak first and then strong.